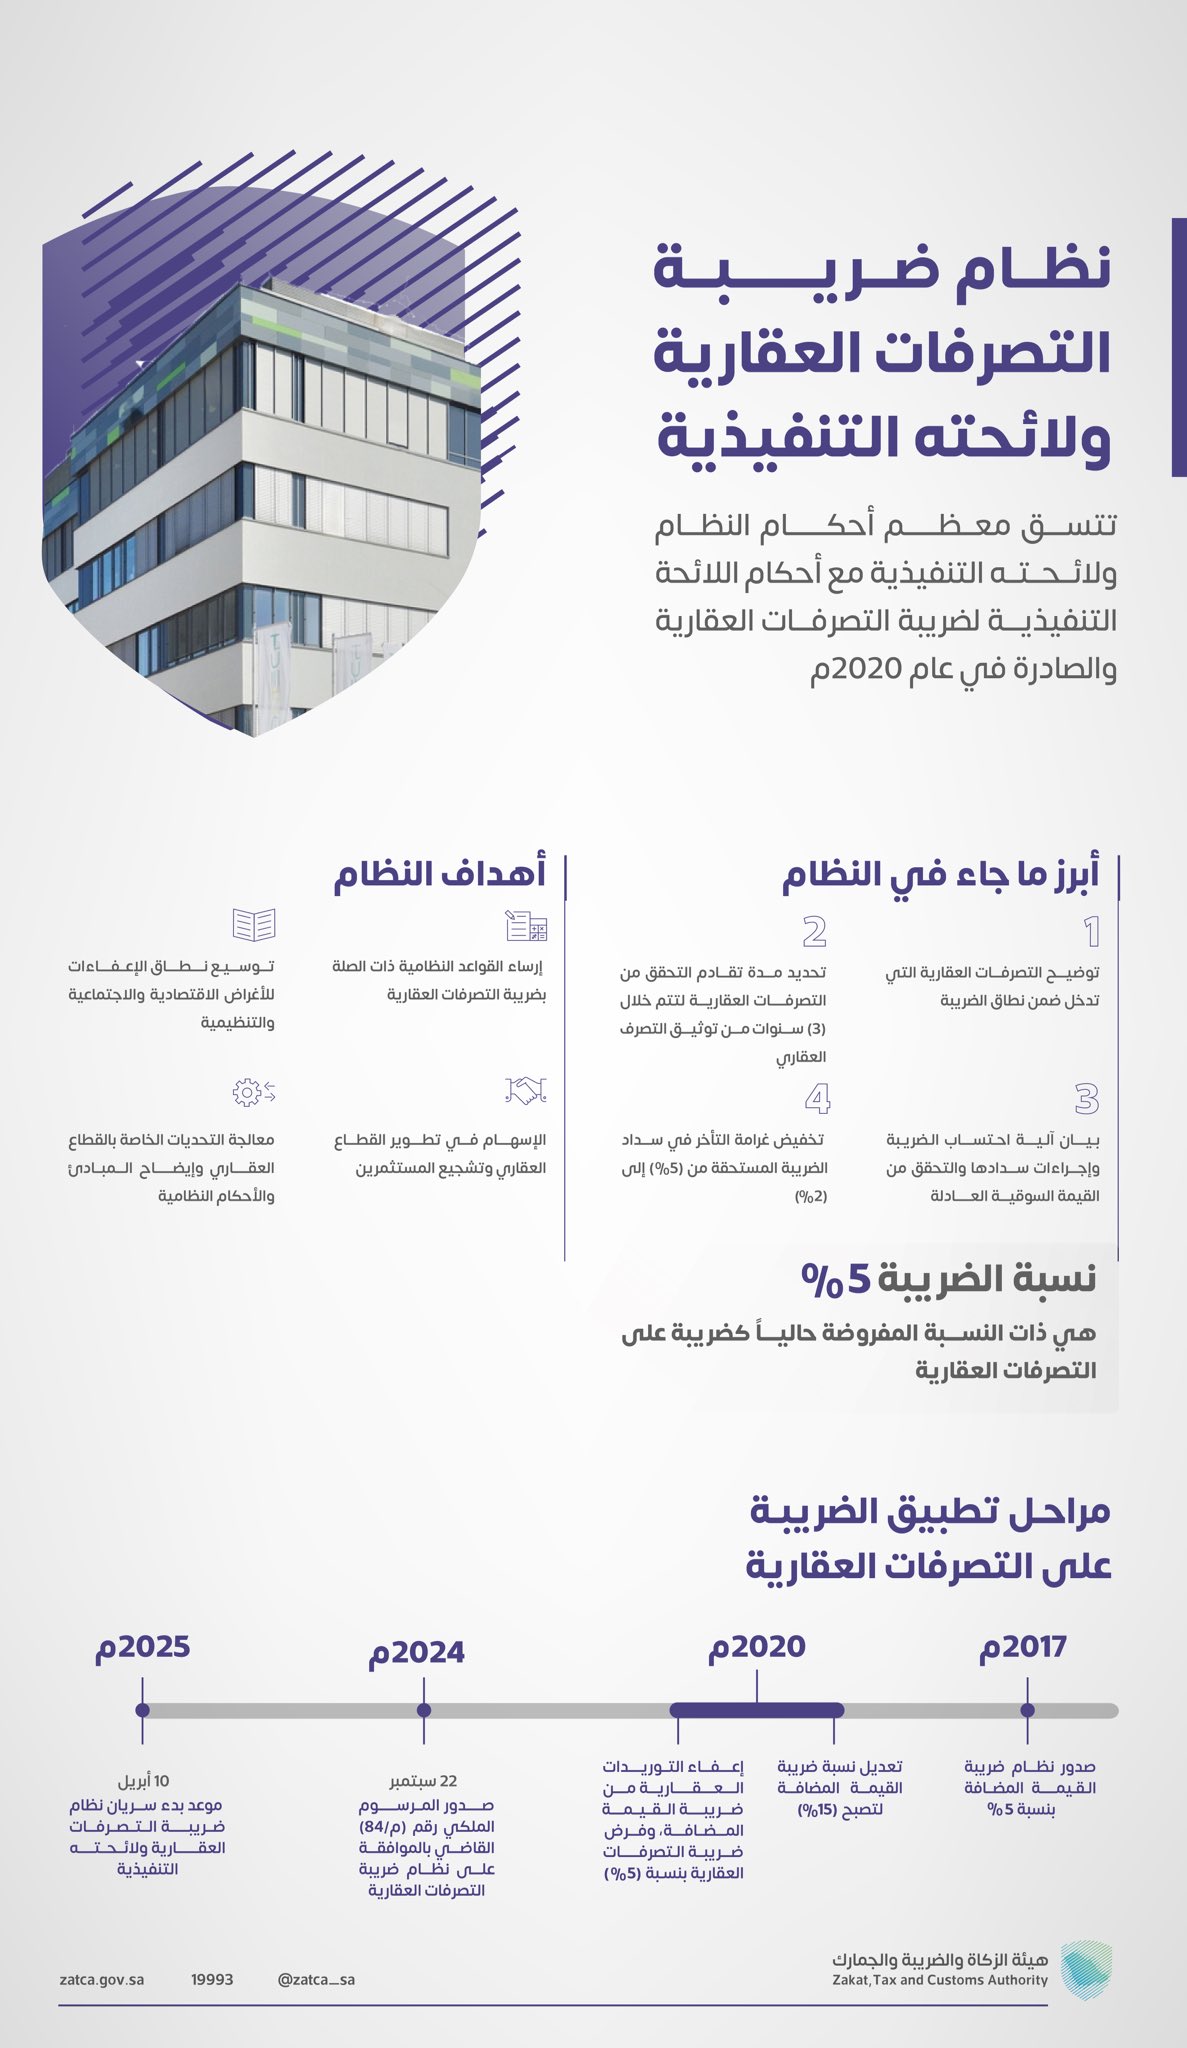

As part of the procedures and efforts to enhance transparency and tax fairness, the Board of Directors of the Zakat, Tax and Customs Authority approved the executive regulations for the Real Estate Transactions Tax System, which aims to regulate the process of imposing tax on real estate transactions in the Kingdom, in line with Saudi Vision 2030. These regulations are a major step towards modernizing the tax systems in the Kingdom, while emphasizing the application of fairness in all stages of real estate transactions.
Tax at a rate of 5% on real estate transactions:
The executive regulations of the Real Estate Transactions Tax Law stipulate a tax of 5% on any real estate transaction, regardless of the property's condition, form, or use at the time of the transaction. This applies whether the transaction involves a whole or part property, a subdivided or jointly owned property, a completed, under-construction, or even off-plan property, and whether or not the transaction is officially documented. The total value of the real estate transaction is calculated based on any consideration agreed upon by the parties involved, whether in cash or in kind, provided it aligns with the fair market value of the property.
Real estate transactions that include tax exemptions:
The regulations established clear criteria and controls regarding cases of full tax exemption. These exemptions include real estate transactions conducted within the framework of estate division according to the regulations in force in the Kingdom, as well as transactions made for the benefit of public, private, or joint endowments registered with the relevant endowment authorities. Exemptions were also specified for real estate transactions between legally licensed charitable organizations, provided that their activities aim to achieve a public interest. Furthermore, exemptions were included for real estate transactions made for the benefit of public entities or projects of public benefit, such as ministries, government agencies, and projects serving the public interest.
Real estate transactions within the framework of financing contracts:
Regarding real estate transactions conducted under Murabaha and Ijarah contracts for the purpose of ownership or financial leasing, the regulations stipulate that tax is levied only on the first transaction resulting from these contracts, from the transferor to the licensed financing entity. Clear conditions were also established for calculating the tax in cases involving real estate included in financing contracts.
This regulation contributes to a significant development in the tax system in the Kingdom of Saudi Arabia, as it strengthens oversight of real estate transactions and clearly defines exemptions for charitable projects, activities, and projects of public benefit. With these amendments, the Kingdom is moving closer to achieving its goals of enhancing transparency and developing the real estate sector in line with Vision 2030.