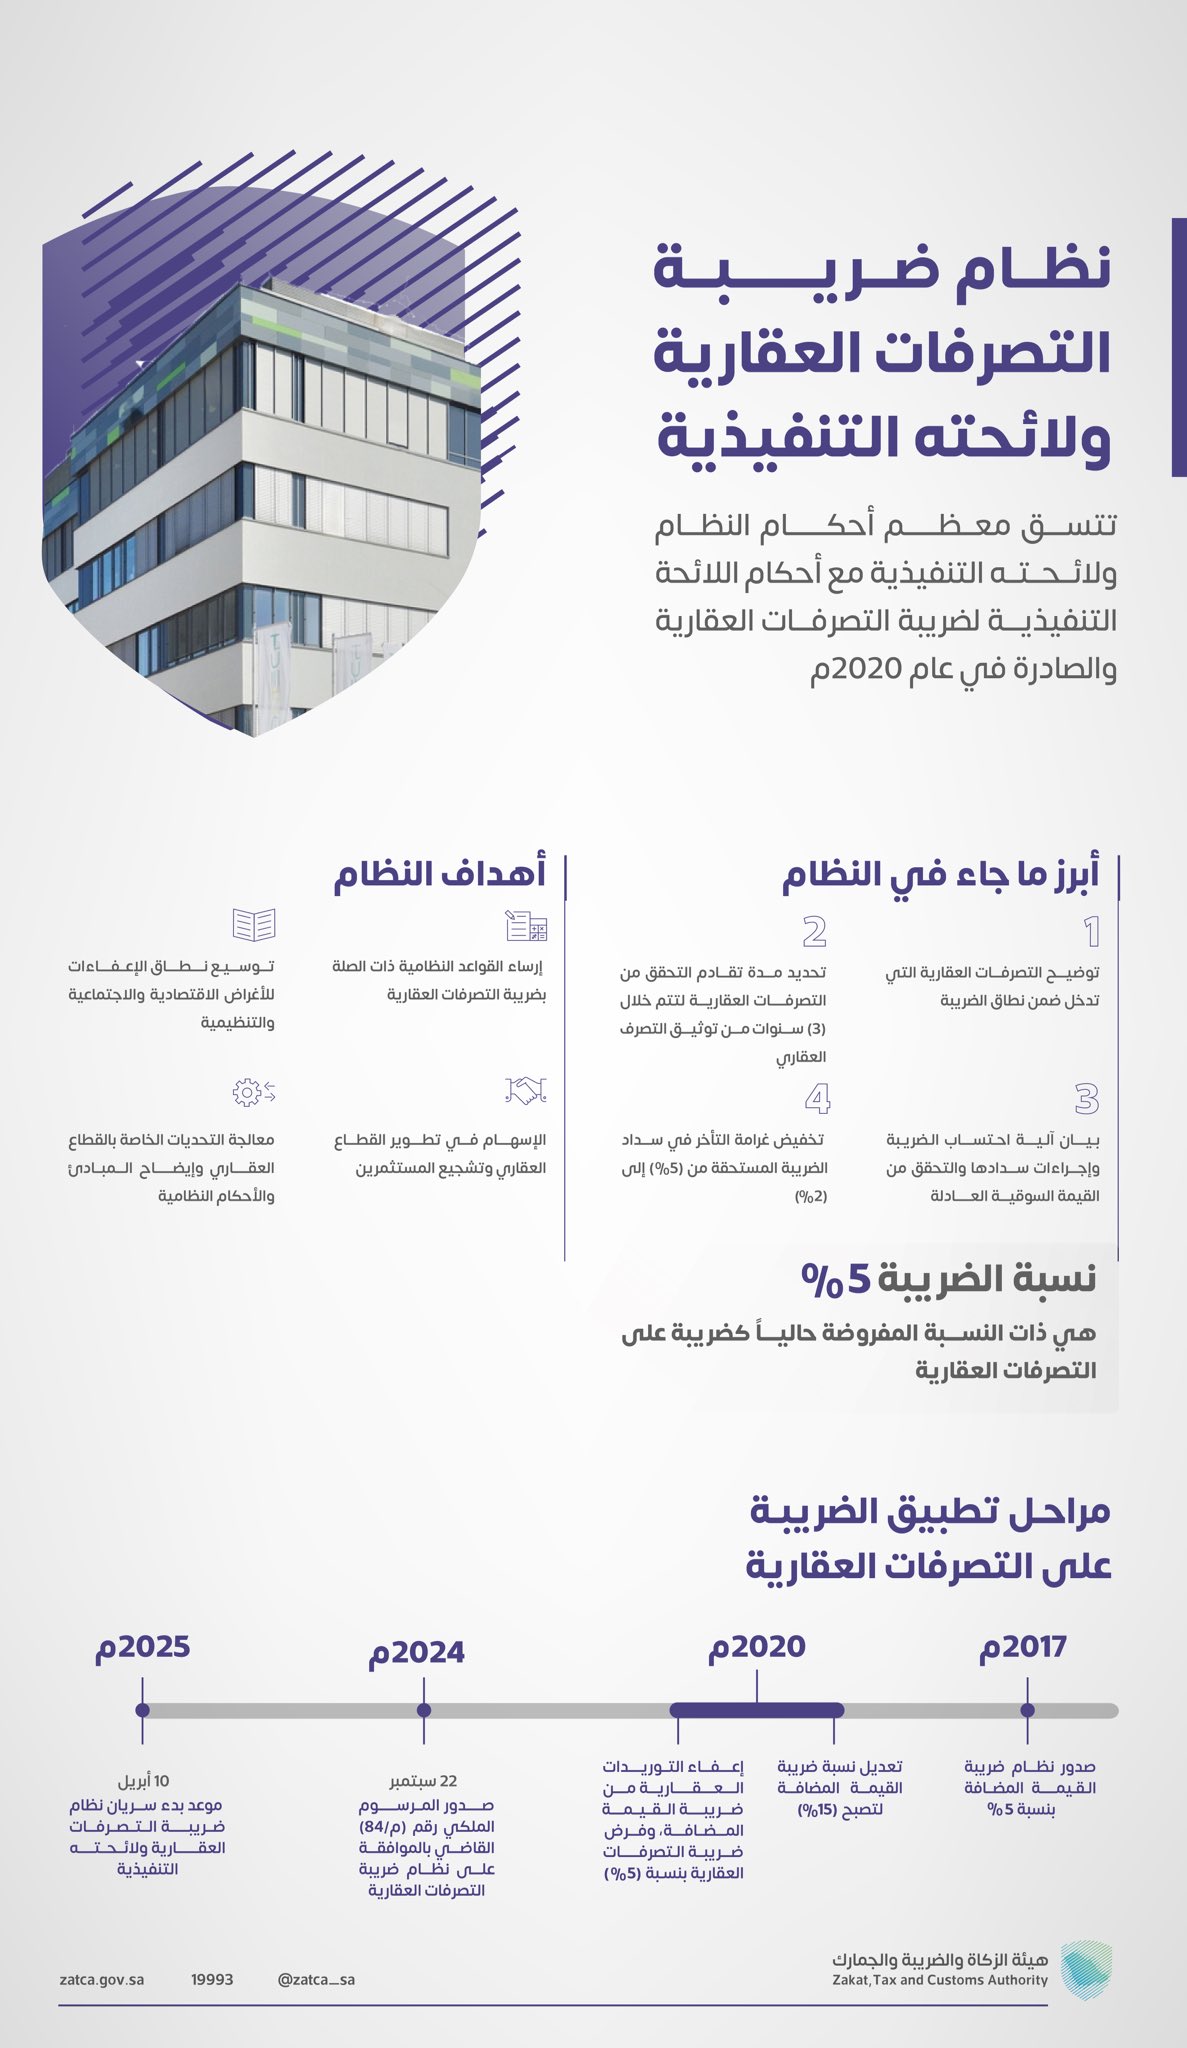

The new real estate transaction tax system begins today, Thursday, replacing the executive regulation in effect for years.
The Board of Directors of the Zakat, Tax and Customs Authority approved the new executive regulation of the real estate transaction tax system, which aims to define the mechanisms and criteria for applying the tax on real estate transactions in the Kingdom.
The Executive Regulation of the Real Estate Transaction Tax System stipulates the imposition of a tax of 5% on any real estate transaction, regardless of the condition of the property, its form, or its use at the time of the transaction. The tax includes real estate transactions, whether they concern the entire property or a part of it, whether this part is freehold or leased. It also extends to completed or still under construction properties or even those listed on the map, regardless of their legal status, whether the transaction has been documented or not.
Regarding the value of the real estate transaction, the regulation specifies that the total value depends on any consideration, whether in cash or in kind, agreed upon between the parties involved. It is required that this value be within the bounds of fair market value, taking into account any special circumstances that may be stipulated by the regulation.
Criteria for full tax exemption:
The regulation sets out a set of criteria for the full exemption from tax, including cases where the inheritance is divided in accordance with the regulations in force in the Kingdom. Real estate transactions carried out without consideration, whether in cash or in kind, for the benefit of a public, private, or joint foundation, are also exempt, provided that the foundation is officially registered with and supervised by the relevant endowments authorities.
The exemptions also include acts carried out by or to a charitable organization licensed in accordance with the regulations, provided that the charitable activities carried out by these organizations are aimed at achieving a public interest and enjoy public benefit status from the competent authority.
Furthermore, real estate transactions carried out for the benefit of a public authority, one of the public legal entities, or public-benefit projects are exempt, provided that the person carrying out the transaction is the relevant entity or another person who obtains a direct or indirect share of the property.