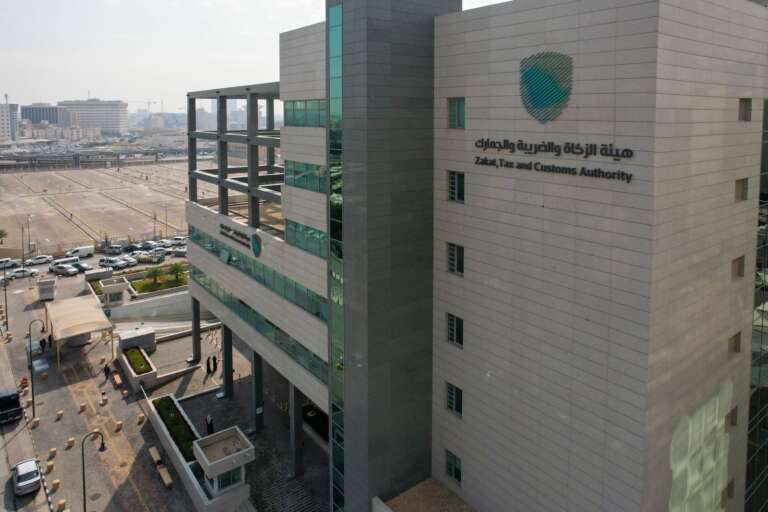
The Zakat, Tax, and Customs Authority has opened a public comment period for the finance and oversight sectors regarding the draft «Classification of Violations and Penalties for the Real Estate Transactions Tax» on the Isti'lal survey platform from September 3 to October 3, 2026, in a move aimed at establishing a clearer framework for classifying violations and determining the associated penalties.
The draft aims to improve the governance of real estate transaction tax enforcement and standardize the mechanism for handling violations, in addition to enhancing clarity and transparency for parties involved in real estate transactions regarding the types of violations, the penalties prescribed for each, and the mechanism for imposing fines.
The proposed classification establishes specific rules for calculating the value of violations, primarily tax evasion violations. The determination of the fine is based on a set of criteria applied collectively according to the relative weight assigned to each criterion, resulting in the determination of the total weight upon which the fine amount is based.
3 Levels of Tax
Evasion Fines The draft measures the extent of tax evasion by calculating the ratio of the evaded tax to the total tax due on the real estate transaction in question.
This ratio is calculated by dividing the amount of tax that went unpaid as a result of the evasion by the total real estate transaction tax due on the transaction before accounting for the impact of the evasion.
According to the proposed classification, this criterion is assigned a relative weight of up to 40%. If the evaded tax constitutes less than 10% of the total tax due, the relative weight is 0%, while it rises to 10% when the ratio ranges between 10% and 25%.
The weight reaches 20% if the evasion rate exceeds 25% and goes up to 50%, and rises to 30% when the rate exceeds 50% and goes up to 90%, while the maximum of 40% applies if the evaded tax exceeds 90% of the total tax due.
Falsified documents and repeat offenses
: The determination of the severity of the violation is not limited to the percentage of the evaded tax; the proposed classification takes into account the nature of the tax evasion and aggravating circumstances, with a relative weight of up to 60%.
The draft bill assigns a weight of 30% in cases where forged, fabricated, or false documents, information, statements, or records—or the equivalent—relating to real estate transactions are submitted, or where any other act is committed with the intent to evade tax.
An additional weight of 30% is also applied if a previous violation of real estate transaction tax evasion has been committed.
According to the draft, "repeat offense" means committing a tax evasion violation within 12 months of the date the Authority’s Governor issued a decision finding the tax evasion violation. If more than one criterion applies to a single violation, the weightings prescribed for each criterion are added together to determine the total weighting, provided that the sum of the weightings does not exceed 100%.
The total weight determines the amount of the tax evasion
fine The draft links the total weight of the violation to the amount of the fine imposed for tax evasion, with penalties ranging from a fine equal to the amount of the evaded tax up to three times that amount.
If the total weight of the violation is less than 40%, the fine is equal to the amount of tax evaded, while it rises to twice the amount of tax evaded when the total weight ranges from 40% to less than 70%.
If the total weight ranges from 70% to 100%, the fine amounts to three times the value of the evaded tax.
This classification is based on the first paragraph of Article 15 of the Real Estate Transactions Tax Law, which stipulates a fine not exceeding three times the amount of the evaded tax in cases of tax evasion, with the same penalty applying to anyone proven to have participated in, aided, or facilitated the evasion.
Fines of up to 50,000 riyals for other
violations The draft also specifies the mechanism for handling other violations of the provisions of the Real Estate Transactions Tax Law and its implementing regulations, excluding cases of tax evasion.
Paragraph 3 of Article 15 of the Law stipulates that anyone who violates any provision of the Law or its regulations shall be punished with a fine not exceeding the amount of tax due or 50,000 riyals, whichever is greater.
According to the proposed classification, the fine for providing incorrect information regarding a real estate transaction ranges from 5,000 to 50,000 riyals; the same fine applies for failure to register a real estate transaction in accordance with the provisions of the Law and its implementing regulations.
Penalties also apply for failing to retain documents and records required for tax purposes for the specified statutory periods; in this case, the fine ranges from 5,000 to 50,000 riyals. As for failure to cooperate with the Authority during audit procedures or failure to provide the requested information when asked, the proposed fine ranges from 1,000 to 50,000 riyals.
The same penalty ranges apply to failure to cooperate with the Authority’s officials during inspection procedures, or failure to allow them access to the books, records, invoices, and accounting documents on file, or to allow them to take and retain copies thereof for audit purposes, with fines ranging from 1,000 to 50,000 riyals.
The draft also specifies a fine ranging from 1,000 to 50,000 riyals for any other violation of any provision of the Real Estate Transactions Tax Law or its implementing regulations.