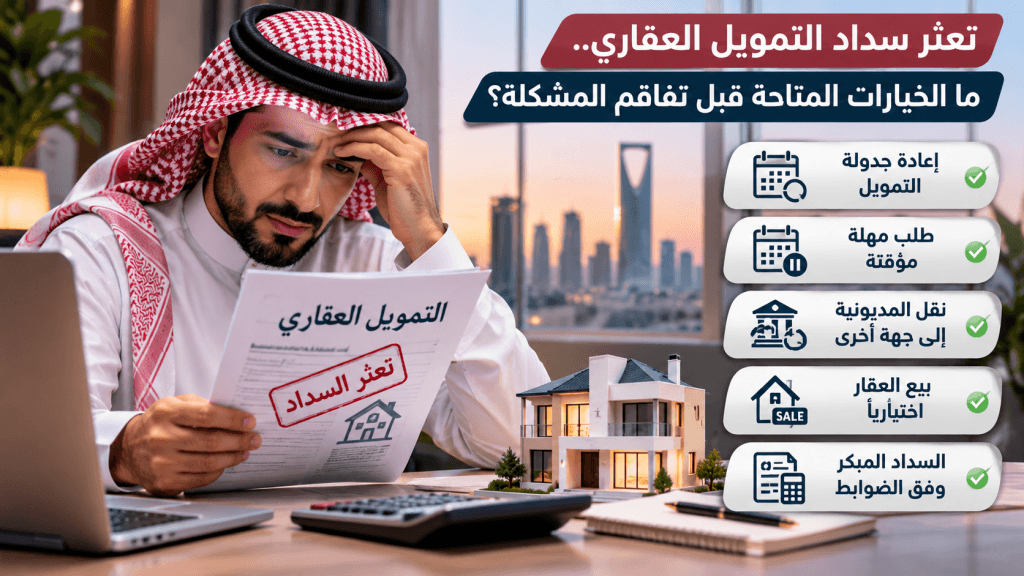

Job loss, reduced income, or increased monthly expenses can transform a mortgage payment from a regular obligation into a burden that is difficult to manage. However, default does not necessarily mean immediate loss of the home. Saudi regulations offer options for debt rescheduling and settlement of obligations, and grant the client a grace period to address the default within the terms and conditions of the contract.
The Saudi Central Bank’s regulations include proactive solutions to deal with indicators of default, including debt rescheduling in specific cases, which allows the customer the opportunity to address their financial situation before obligations worsen.
When is a client classified as delinquent?
Article Nine of the Saudi Central Bank’s collection regulations and procedures sets out criteria for default on monthly mortgage installments. A customer is considered to be in default if they fail to pay installments in full or in part for three consecutive months, or if they are late in paying five separate installments, provided that the delay in each installment is seven working days or more, according to the period specified in the regulations, which is every five years of the financing contract period.
These periods should not be understood as a grace period that allows the client to ignore the installments or postpone contact with the financier until they are reached. The model model for the real estate financing contract in the form of Murabaha stipulates sending a notice of delay when seven working days have passed from the date of the installment due, with an explanation of the obligation to pay.
Rescheduling: The most important option when income decreases
Requesting debt rescheduling is one of the most prominent available options, but its conditions vary depending on the reason for the change in the client's financial situation. If it is proven that the client's circumstances have changed involuntarily and he has become vulnerable to default, the regulations require the financing entity to offer rescheduling without granting him new financing, without imposing additional fees, and without changing the agreed-upon term cost. If the client requests rescheduling and submits the required documents, it must be implemented within a period not exceeding 20 working days from the date of completion of the documents, with the deduction of installments postponed until the rescheduling procedures are completed.
If the change in circumstances is optional, such as early retirement or resignation, the financing entity may offer rescheduling, with the possibility of changing the cost of the term, without additional fees, and within the regulatory period specified after the completion of the documents.
Another important case is if the reason for the default is due to the financing entity's failure to assess the client's creditworthiness, including exceeding the legally specified deduction rates, then the regulations require it to reschedule without new financing, additional fees, or a change in the cost of the term.
Is it possible to request a deferral of the installment payment or a reduction in its value?
The customer can negotiate with the financing entity to request a temporary grace period or to modify the repayment schedule to suit his income, but a distinction should be made between the rescheduling regulated by the Central Bank’s instructions and a request to postpone an installment or suspend payment, as there is no general and absolute right to postpone installments simply by submitting a request.
Therefore, it is important for the client to have a realistic assessment of their financial capabilities and to request a written offer that clarifies the new monthly payment, the remaining loan term, the total amount due, the cost of the loan, and the annual percentage rate (APR). Reducing the monthly payment by extending the loan term may alleviate the monthly burden, but it could also increase the client's total payment over the contract, depending on the rescheduling terms.
Debt transfer or property sale: options worth considering
If the financial capacity no longer allows for continued financing, the client can inquire about the possibility of transferring the debt to another financing entity or refinancing, provided that the new entity agrees and passes its credit assessment, with a review of the total cost before making a decision.
Alternatively, a voluntary sale of the property and repayment of the debt from the proceeds can be considered, after agreeing with the lender on settlement procedures, mortgage release, and transfer of ownership. This option may be less costly than resorting to a forced sale, but the decision requires calculating the property's market value compared to the remaining loan balance and the costs associated with terminating the contract.
If the customer chooses early repayment, the Central Bank’s instructions do not allow him to be charged the cost of the term for the remaining period, while allowing the financier a specific compensation in accordance with the regulations, which includes the cost of reinvestment not exceeding the cost of the term for the three months following repayment, and some non-refundable third-party expenses when they are documented and legally due.
Death or total disability: Regulatory exemption in specific cases
The Saudi Central Bank's regulations include special protections in cases of customer death or total disability. Financing entities are obligated to exempt the customer and their guarantor from the amounts claimed under the contract, according to the ratio of the financing obligations, and to complete the procedures within a maximum period of 30 days from receiving the death certificate or the approved medical report of total disability.
The procedures include refunding any overpayments made after the date of death or incapacity, transferring ownership of the financed asset to the client or their heirs, or releasing the mortgage, as applicable. It should be noted that the regulation includes exceptions, such as financing contracts concluded before October 1, 2018, and certain specific cases and reasons outlined in the regulatory text. Therefore, the eligibility criteria for the exemption should be reviewed for each individual contract and case.
Does default mean the property will be sold immediately?
Delay in payment does not automatically transfer ownership of the house to the financing entity, as the registered mortgage system allows the mortgagee to take action to seize and sell the mortgaged property if the debt is not paid, but this is done after notifying the debtor and in accordance with the enforcement system procedures.
The model mortgage finance contract in the form of Murabaha also stipulates that the notice of default must explain the reasons for the default, how to correct it, and the grace period granted to the client before the enforcement procedures on the guarantees begin, provided that this grace period is not less than 20 working days, in addition to explaining how to stop the enforcement procedures.
Therefore, ignoring notifications or failing to respond to the financing entity puts the client in a more difficult position, while an early response provides an opportunity to negotiate and document possible solutions.
What does the customer actually do?
When the first signs of difficulty in repayment appear, it is advisable to follow these steps:
1- Officially contact the financing entity and request a rescheduling inquiry, explaining the reason for the change in income and attaching supporting documents.
2- Request a detailed statement of account showing the installments paid and overdue, the principal of the debt, the cost of the term, and additional fees and costs.
3- Presenting a realistic repayment offer that is appropriate to the current income, and not agreeing to a new schedule before knowing its total cost.
4- Keep all notices, correspondence, rescheduling requests, and responses from the financing entity.
5- Submitting a complaint to the Saudi Central Bank if the financing entity does not comply with the regulations or does not address the objection according to the approved procedures.
The Saudi Central Bank's platform allows for the submission of electronic complaints against banks and finance companies, along with the attachment of supporting documents and tracking of the request.
Read also:
Before selling your property... 5 obligations to review before transferring ownership