From paper to algorithms, from human employees to intelligent machines, the mortgage finance sector is undergoing a transformation with the introduction of artificial intelligence into loan application evaluation. Will this usher in an era of transparency and efficiency? Or will it raise concerns about privacy and hidden biases?
Mortgage loan valuation: From traditional processes to smart transformation
In the traditional system, banks and mortgage finance companies rely on human analysts to examine loan applications, review financial documents, assess property value, and study the borrower's creditworthiness.
However, this process takes a long time, is subject to individual interpretations, and may be affected by subjective factors.
This is where artificial intelligence (AI) comes in to reshape the landscape, through big data analysis models and machine learning algorithms that can make accurate decisions with incredible speed.
How is artificial intelligence used in evaluating mortgage loans?
Borrower creditworthiness analysis
The algorithms use financial and non-financial data, such as credit history, income level, monthly obligations, and even spending behaviors.
It can detect indicators of default or repayment capacity that do not readily appear in traditional models.
Accurate property valuation
The algorithms rely on live market data, including similar property selling prices, geographic location, infrastructure, and market trends.
Image analysis techniques are used to review property images and verify their actual condition.
Expediting procedures and approvals
Through the complete automation of the process, requests are evaluated within minutes instead of days.
The need for human intervention is reduced, which limits errors and lowers operating costs.
Fraud detection
It analyzes data patterns to detect forged documents or suspicious transactions.
It is integrated with Know Your Customer (KYC) systems and identity recognition technologies to verify the accuracy of information.
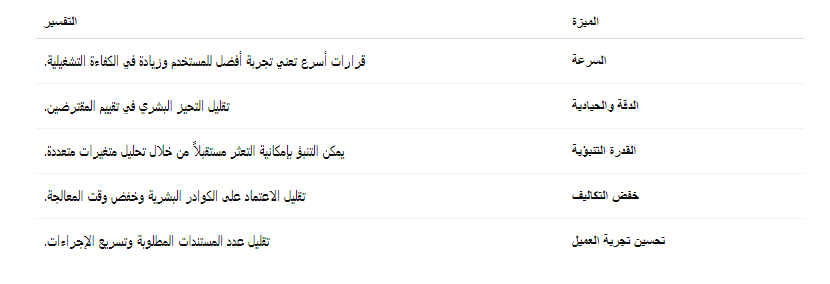
Advantages of relying on artificial intelligence in the real estate finance sector
Challenges and concerns
Despite the advantages, the use of artificial intelligence is not without its challenges:
Algorithm bias
If models are trained on biased historical data, decisions may continue to repeat past mistakes, such as discrimination against certain groups.
Lack of transparency
Algorithm decisions are often a “black box,” difficult to explain to the customer in case of rejection.
Privacy and data protection
Relying on massive amounts of sensitive data raises questions about protecting user privacy.
Over-reliance on machines
In exceptional or complex cases, algorithms may fail to read the human context or personal circumstances.
Examples of AI adoption in real estate finance
Global banks such as JPMorgan and HSBC already use artificial intelligence systems to analyze loans and assess risks.
Financial technology (FinTech) companies such as Blend and Zest AI are providing smart solutions to traditional banks in the field of mortgage loan evaluation.
In the Arab region, some banks in the UAE and Saudi Arabia have begun testing artificial intelligence solutions within their credit models.
Is artificial intelligence an alternative or a complement?
Experts believe that artificial intelligence does not completely eliminate the role of humans, but rather complements it.
While the machine handles the repetitive analytical tasks, the human element remains an important role in the final review, handling exceptional cases, and communicating with clients.
Smarter and more transparent financing
With the increasing demand for mortgage loans in emerging markets, and the growing need for accurate and rapid financial decisions, artificial intelligence is an indispensable tool in the near future.
With ethical controls and data protection in place, this technology can strike a balance between innovation and efficiency, and between fairness and transparency, and open the door to more inclusive and equitable funding opportunities.