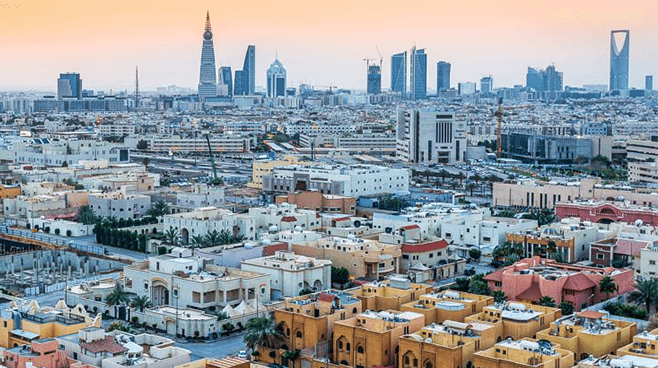
The market for apartment market in Riyadh underwent notable shifts during the period from the first quarter of 2023 through the second quarter of 2026, as the impact of decisions Real Estate Balance on rental activity, sales, and prices, at a time when the market took different paths across different property types and neighborhoods.
According to a report issued by «Jiad Financial» titled «Changes in the Riyadh Apartment Market Following the Real Estate Balance Decisions,» apartment sales declined at a much faster rate than prices, with the number of apartments sold falling by 88% from a peak of 1,692 apartments in the first quarter of 2024 to 195 apartments in the second quarter of 2026, while the average apartment sale price fell by only 17%, from a peak of 744,000 riyals in the second quarter of 2025 to 616,000 riyals in the second quarter of 2026.
Rents... A strong rise before stabilization, followed by a correction
The report tracks a different trajectory for rents, whose annual average rose by 76% from the first quarter of 2023 through the third quarter of 2025, the quarter in which the decision to freeze rents was issued, before the average declined by 14.7% through the second quarter of 2026.
Among Riyadh’s districts, Central Riyadh recorded the largest increase, with the average annual rent rising from 25,000 riyals in the first quarter of 2023 to 45,800 riyals in the fourth quarter of 2025, an increase of 121%.
Northern Riyadh recorded an increase in the average rent of 57% through the third quarter of 2025, before declining by 14.5% in the second quarter of 2026, while average rents in eastern Riyadh rose by 73% before declining by 13.6%.
In western Riyadh, the average rose by 71% through the third quarter of 2025, then fell by 16.1% in the second quarter of 2026, while southern Riyadh recorded growth of 58% before declining by 14.0%.
The report indicates that the slowdown in rental growth began a full year before the price freeze decision, with the compound annual growth rate reaching 31.3% at one stage, then slowed to 17.2%, before turning into a negative compound annual growth rate of 19.1% in the final phase, while the compound annual growth rate for the entire period was 13.4%.
24 neighborhoods recorded a decline in the first quarter of 2026
Neighborhood data reveals the extent of the correction following the real estate stabilization decisions. In the fourth quarter of 2025—the first full quarter following the issuance of the rent stabilization decision—20 out of 25 neighborhoods recorded a decline in rents.
In the first quarter of 2026, the decline expanded to include 24 out of 25 neighborhoods—the broadest decline during the period covered by the report.
In the second quarter of 2026, 13 neighborhoods recorded a decline in rents, while rents rose in 12 neighborhoods.
When comparing the third quarter of 2025 to the second quarter of 2026, average apartment rents in most Riyadh neighborhoods fell by percentages ranging from 0.4% to 24.1%.
The Al-Mursalat neighborhood recorded the largest decline, at 24.1%, equivalent to 11,875 riyals annually, as the average rent fell from 49,316 riyals to 37,441 riyals.
Al-Dar Al-Bayda saw a decrease of 21.6%, Dhahrat Labban 21.0%, Al-Olia 20.5%, Al-Nargis 19.0%, Al-A’arid by 18.2%, Al-Wazarat by 18.0%, and Al-Khaleej by 17.1%.
In contrast, Al-Ward was the only neighborhood where the average rent has risen since the quarter preceding the rent freeze decision, by 0.3%, while Arqa was the closest to stability, with a decline of only 0.4%.
The Al-Mursalat neighborhood recorded the largest surge before the decision
Before the decision to freeze rents, some neighborhoods saw significant increases, with the Al-Mursalat neighborhood being the most notable, as the average rent rose from 23,071 riyals to 49,316 riyals, an increase of 114%, before recording the largest decline among neighborhoods following the decision, falling to 37,441 riyals—a 24.1% drop. In Al-Suleimaniyah, the average rent rose from 24,923 riyals to 46,047 riyals, an increase of 85%, before falling to 41,012 riyals, a decrease of 10.9%.
As for Arqa, the average rent there rose from 27,472 riyals to 38,125 riyals, an increase of 39%, then fell by only 0.4% to 37,983 riyals following the rent freeze decision. In Al-A'arid, the average rose from 25,952 riyals to 45,544 riyals, an increase of 75%, before falling to 37,234 riyals in the second quarter of 2026, a decrease of 18.2%.
Significant Gap in Neighborhood Rents
Average apartment rents over the last four quarters—from the third quarter of 2025 to the second quarter of 2026—ranged from 19,000 to 52,000 riyals per year.
The weighted average rent across neighborhoods was 34,000 riyals, while Al-Malqa recorded the highest average at 51,600 riyals, followed by Al-Olaya at 48,600 riyals, Al-Narges at 45,600 riyals, Al-Suleimaniyah at 45,200 riyals, and Al-Yasmin at 44,800 riyals. At the other end of the spectrum, the average in Al-Shafa was 19,300 riyals—the same level recorded in Badr—while in Tuwaiq it was 20,600 riyals, Al-Dar Al-Bayda at 21,200 riyals, Al-Aziziyah at 22,100 riyals, and Namar at 22,800 riyals. The rent for an apartment in Al-Malqa is approximately 2.7 times that in Al-Shifa.
Sales Are Declining More Sharply
In the home ownership market, the gap between sales volume and prices is clearly evident. Apartment sales totaled 1,692 units in the first quarter of 2024, before gradually declining to 195 units in the second quarter of 2026—a decrease of 88%.
Total apartment sales also fell from 3,304 units in the first half of 2024 to 526 units in the first half of 2026, a decline of 84%.
In contrast, the average sales price per unit remained relatively stable, starting at 633,000 riyals in the first quarter of 2023, peaked at 744,000 riyals in the second quarter of 2025, and ended at 616,000 riyals in the second quarter of 2026.
Al-Narges and Al-Malqa… Sales Declined Despite Price Differences
When comparing sales in each neighborhood in 2024 to the last four quarters from the third quarter of 2025 to the second quarter of 2026, most neighborhoods recorded a clear decline in sales volume.
Al-Malqa saw the largest decline, with sales falling from 756 apartments in 2024 to 69 apartments in the last four quarters—a decrease of 91%. In Al-Narges, sales fell from 1,256 apartments to 313 apartments, a decrease of 75%, while in Al-A'arid, sales dropped by 85% from 487 to 74 apartments, and in Qurtuba by 90%, from 403 to 41 apartments. Sales also declined in Tuwayq by 78%, in Al-Yasmin by 68%, in Al-Dar Al-Bayda by 67%, in Al-Aziziyah by 72%, in Al-Mahdiyah by 71%, in Namar by 62%, Suleimaniya (88%), Al-Sahafa (55%), and Al-Yarmouk (66%).
Al-Shifa was the only exception in the data presented, as its sales rose 10%, from 91 apartments in 2024 to 100 apartments over the last four quarters.
Prices Hold Steady in Some Neighborhoods Despite Declining Demand
Despite the sharp drop in the number of apartments sold, sales prices continued to rise in a number of neighborhoods. Al-Sahafa recorded the largest increase in the average sales price, rising 28% from 1.069 million riyals to 1.364 million riyals, despite a 55% decline in sales. In Badr, the average price rose 25% from 289,000 riyals to 362,000 riyals, while sales fell 35%.
In Al-Narges, the average apartment price rose by 17% from 741,000 riyals to 869,000 riyals, despite a 75% decline in sales. The average price also rose in Casablanca by 15%, in Al-Mahdiya by 15%, in Tuwaig by 10%, and in Al-Aziziyah by 3%.
In contrast, the average price in Al-Malqa fell by 15%, from 920,000 riyals to 780,000 riyals, coinciding with a 91% decline in sales.
Al-Olaya had the highest average selling price over the last four quarters at 1.372 million riyals, followed by Al-Sahafa at 1.364 million riyals, while the average price in Al-Shafa was 306,000 riyals, meaning that the price of an apartment in Al-Olaya is about 4.5 times the average price in Al-Shafa.
Rents Outpace Sales Prices
The diverging trends in rents and sales prices have reshaped rental yields in a large number of Riyadh neighborhoods.
From the first quarter of 2023 through the second quarter of 2026, the 50% rent index rose, while the 3% sales price index declined, resulting in a cumulative gap of 53 percentage points between the two indices, which directly led to higher rental yields in most neighborhoods.
Qurtuba topped the list of neighborhoods in terms of rental yield growth, rising from 5.0% in 2024 to 7.1% over the last four quarters, an increase of 2.1 percentage points.
Al-Ramal saw an increase of 1.3 points, Al-Malqa 1.1 points, Al-Shafa 1.0 points, Al-Olia 0.9 points, Al-Aared 0.8 points, and Al-Aziziyah 0.7 points.
In contrast, the yield in Casablanca fell from 6.9% to 6.4%, and in Nargis from 5.8% to 5.2%, and in Al-Sahafa from 3.8% to 3.2%, while Badr recorded the largest decline, from 6.3% to 5.3%.
Real Estate Balancing Decisions
The report links these shifts to the broader context of real estate balancing decisions implemented in Riyadh during 2025. On March 29, 2025, the moratorium was lifted on 81.48 km² of land north of Riyadh, with 40,000 residential plots to be granted annually for a period of five years at a price not exceeding 1,500 riyals per square meter.
On April 29, 2025, fee brackets for undeveloped land were approved, ranging from 10% to 2.5% depending on the bracket.
Then, on September 25, 2025, a decision was issued to freeze residential and commercial rents in Riyadh until September 2030, using the value of the most recent contract registered on the «Ejar» platform as a reference.
On October 9, 2025, the moratorium was lifted on approximately 33.24 km² of land west of Riyadh along Wadi Hanifa, in accordance with the Wadi Hanifa urban code.
A sample reflecting the general market trend
The Jiad Financial report was based on data from 25 neighborhoods in the city of Riyadh, covering the period from the first quarter of 2023 to the second quarter of 2026, using data from the Real Estate Registry and the Ministry of Justice, with measurements standardized based on a 100-square-meter apartment.
The dataset comprises 652,798 rented apartments and 15,446 sold apartments.
The rent analysis is based on the median rent within each neighborhood for each quarter, while the sales analysis is based on the «Average» apartment price calculated from all registered transactions, using a weighted average when aggregating results from multiple neighborhoods or districts. The report indicates that the trend in average apartment sales prices in the sample aligns with the general trend in average apartment sales prices in the city of Riyadh, despite differences in coverage scope and calculation methodology, with a correlation coefficient of 0.912, while R² was approximately 0.831, indicating that about 83% of the variation in the general trend of the Riyadh City index is explained by the sample according to the methodology used.